Most Common Business Policies
A single slip on a wet shop floor, a delivery van fender-bender on the BQE, or a ransomware attack on your online ordering system: any one of these events can drain a small flower shop's bank account in days. New York florists juggle perishable inventory, tight margins, and a regulatory environment that demands specific employer-provided coverages. If you're wondering what insurance a New York florist actually needs, the answer spans liability, property, auto, cyber, and workers' compensation, each tailored to risks that are specific to the floral trade. The stakes are high. A single uninsured claim can cost more than an entire year of premiums, and New York's courts and regulators aren't forgiving toward businesses that skip required coverage. Whether you run a boutique studio in Brooklyn or a multi-location operation upstate, understanding these policies isn't optional. It's the difference between surviving a bad month and closing your doors for good. This guide breaks down each coverage type, explains what New York State law requires, and helps you decide how much protection your shop really needs.
Why New York Florists Face Unique Risks
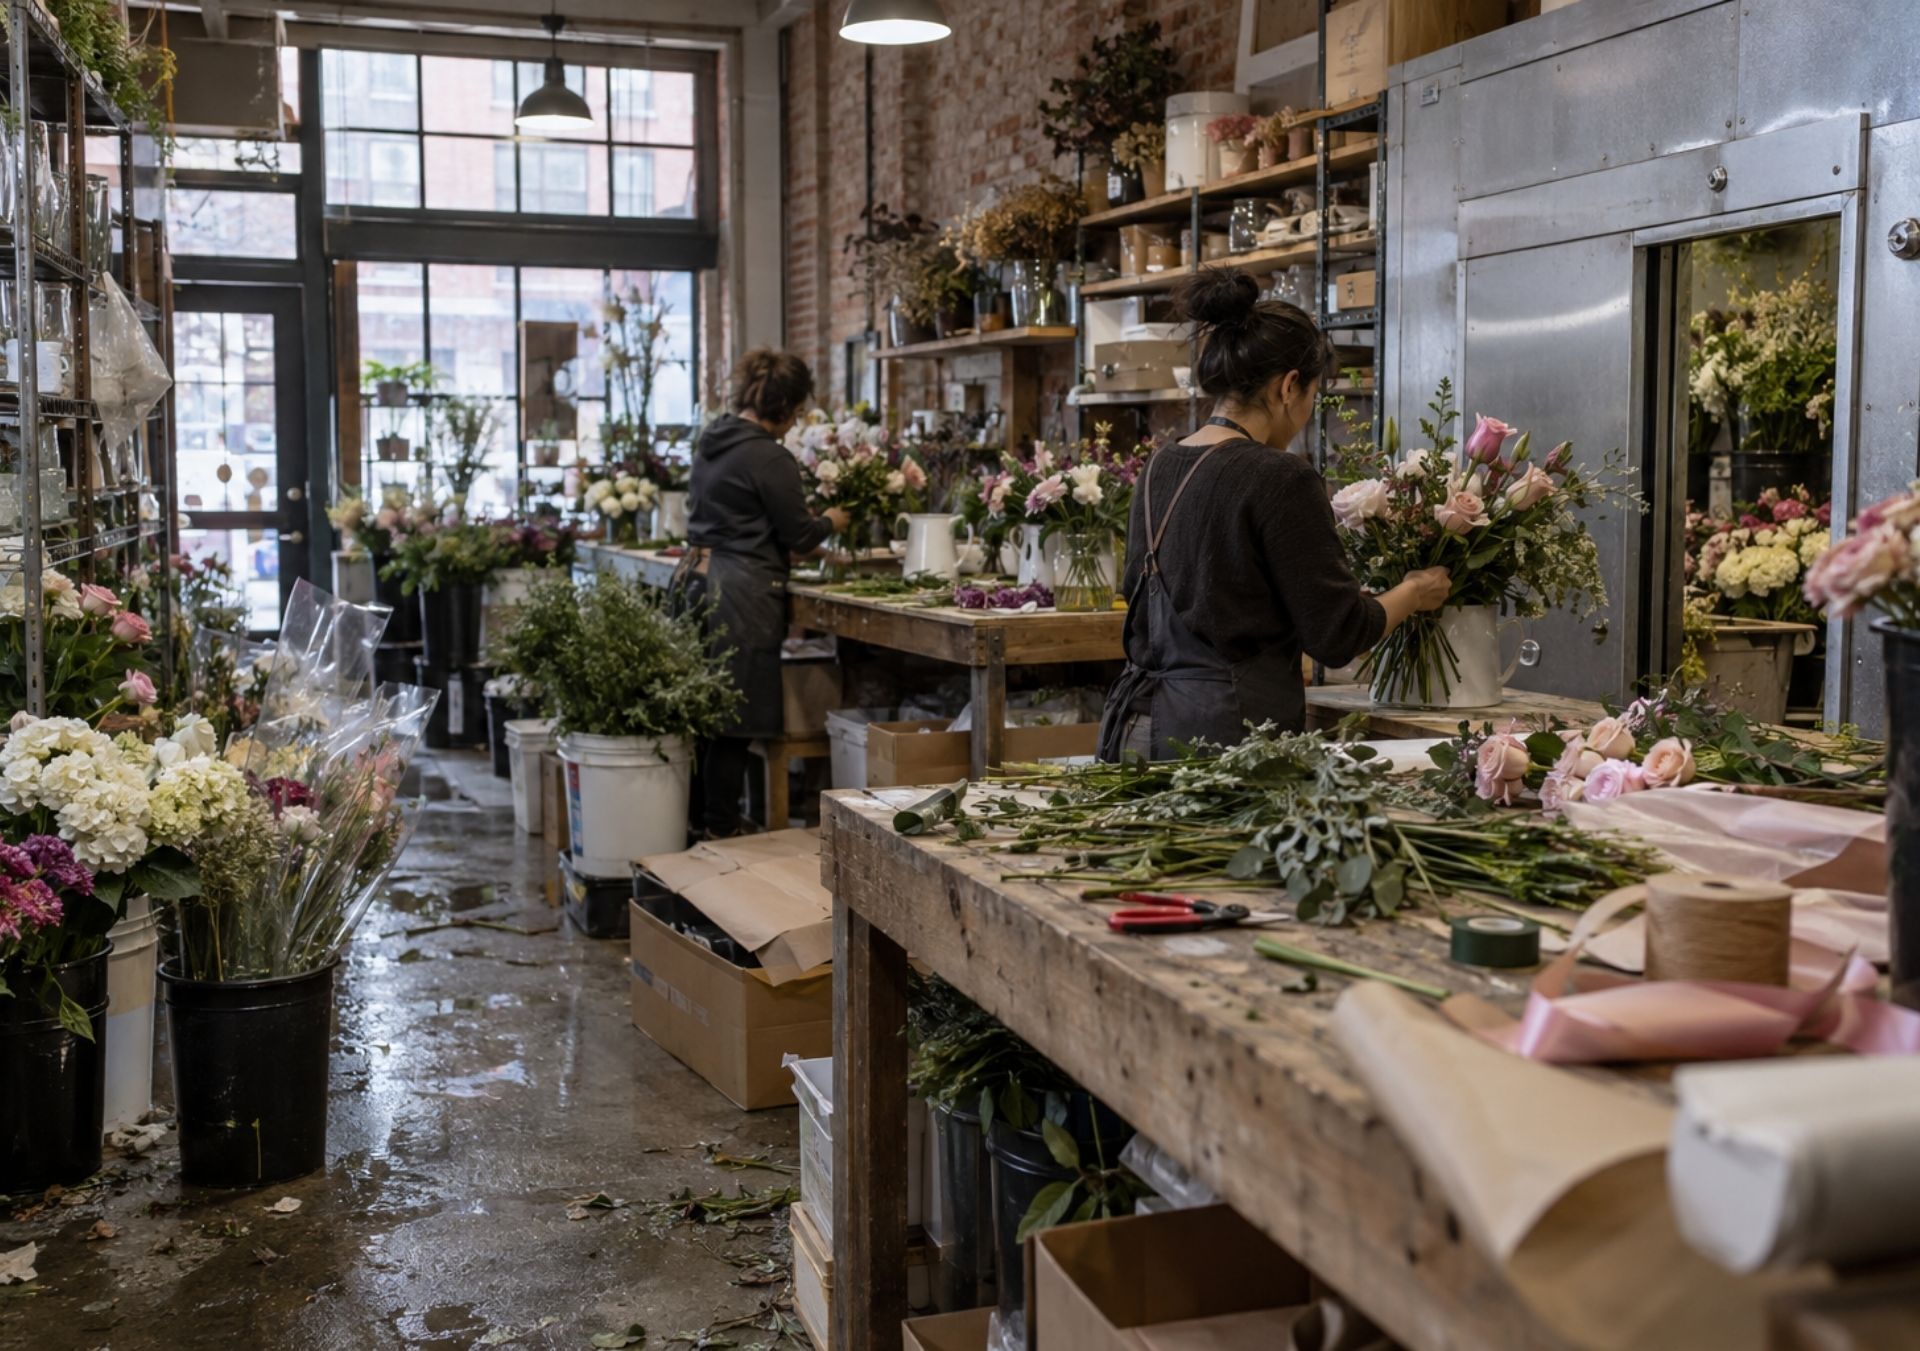
Flower shops aren't quiet, low-risk retail stores. Your staff handles sharp tools, chemical preservatives, and heavy potted plants daily. Walk-in customers navigate narrow aisles lined with water-filled vases on slippery tile floors. Delivery drivers fight New York City traffic or navigate icy upstate roads in January, all while hauling arrangements that need to arrive intact and on time.
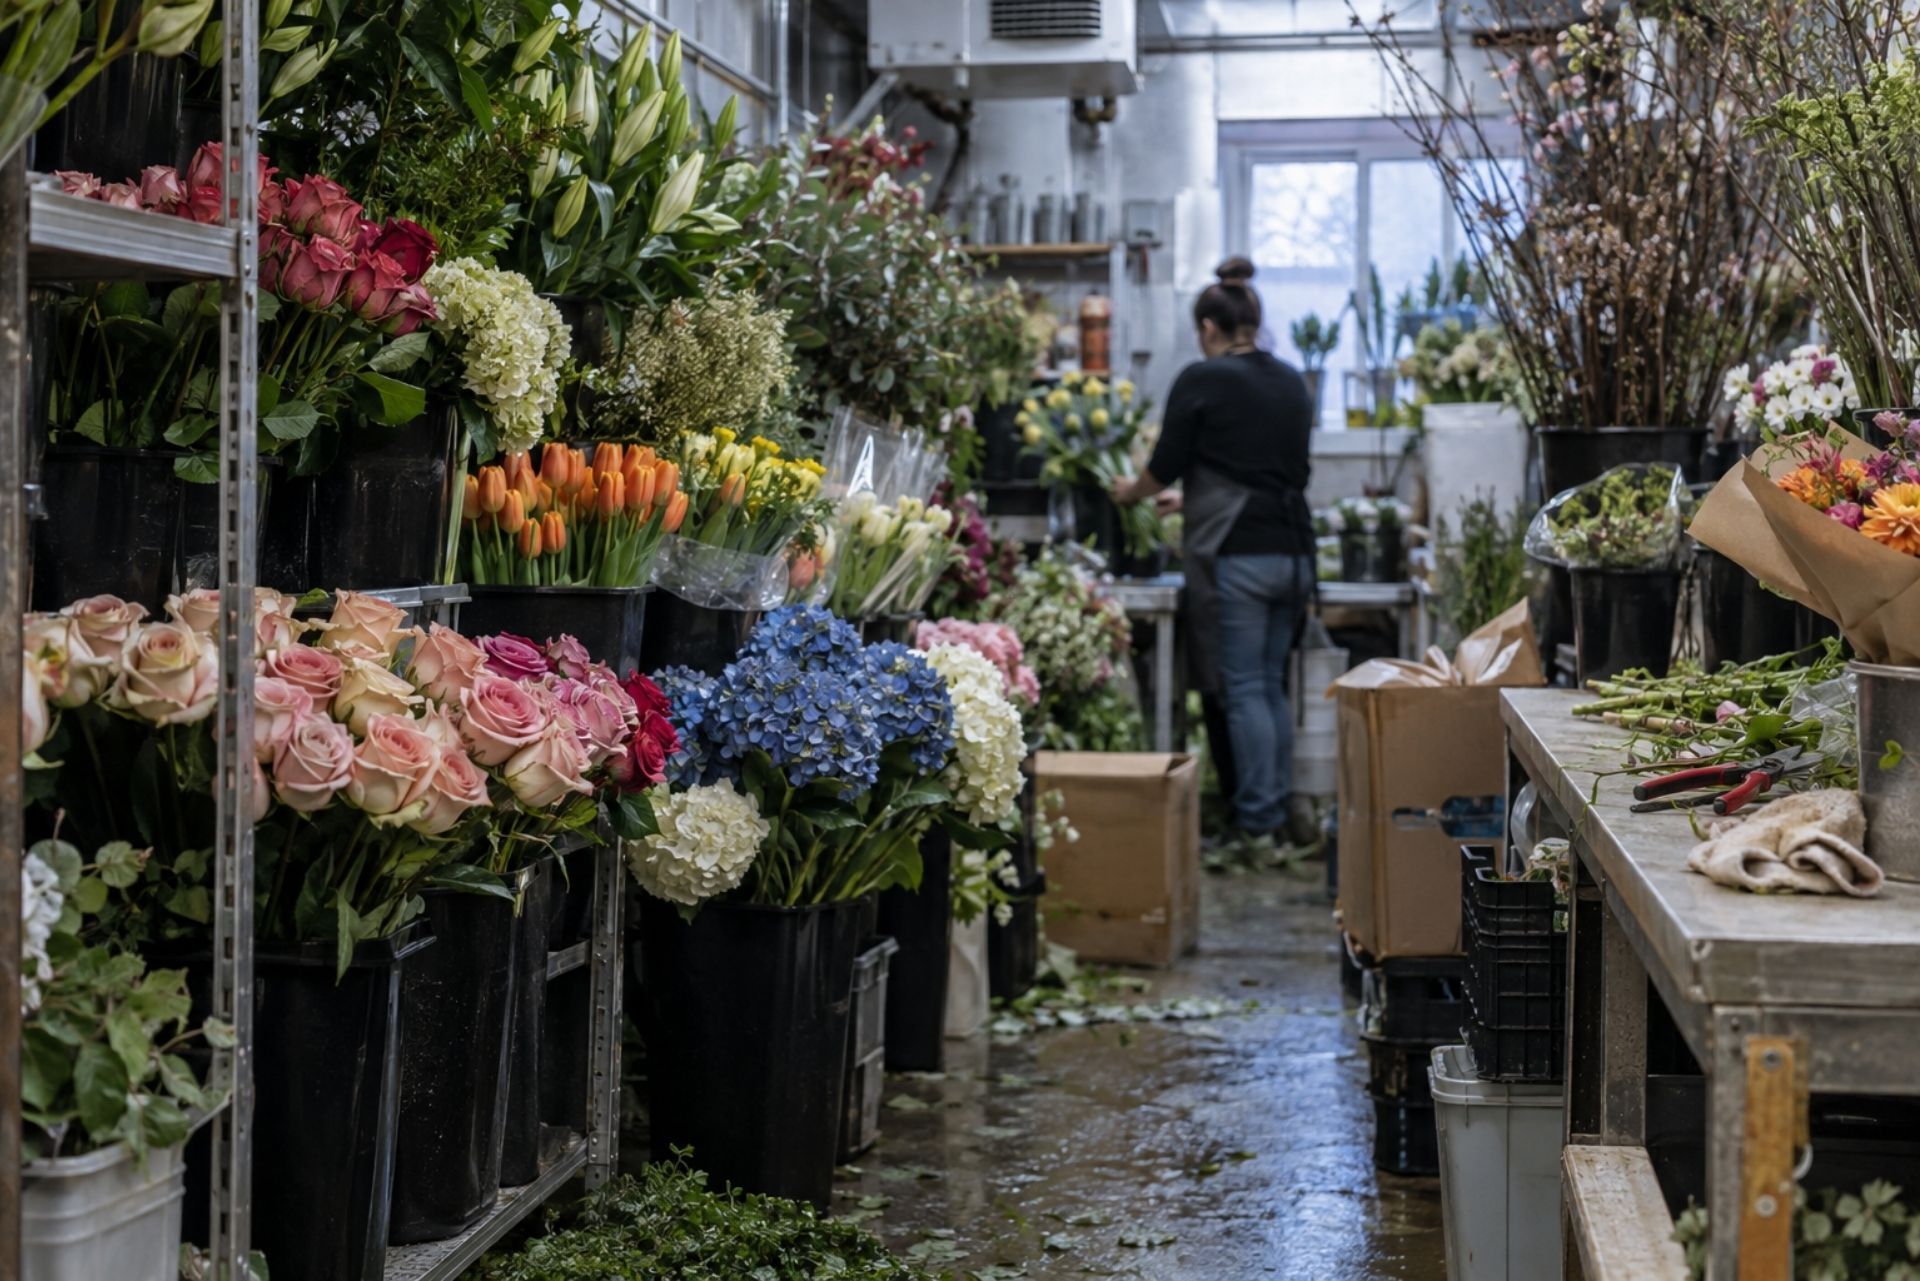
Perishability adds another layer. A cooler failure on a July weekend can destroy thousands of dollars in roses and hydrangeas before Monday morning. The floral industry's mid-year review for 2026 highlights how supply chain volatility and rising wholesale costs have made inventory losses even more painful than they were a few years ago.
Then there's the digital side. Most florists now rely on e-commerce platforms, POS systems, and wire services. That means you're storing customer credit card data and personal information, which makes you a target for cybercriminals. A data breach doesn't just cost money in recovery: it costs customer trust. New York florists face a combination of physical, logistical, and digital risks that few other
small retailers share.
Foundational Coverage: General Liability and Property Insurance
These two policies form the bedrock of any florist's insurance program. You can think of them as the minimum responsible starting point before layering on specialized coverage.
General Liability for Customer Injuries and Property Damage
General liability (GL) pays for third-party bodily injury and property damage claims. If a customer slips on spilled water near your display cooler and breaks a wrist, your GL policy covers their medical bills, legal defense costs, and any settlement or judgment. It also covers damage you cause at a client's venue. Picture a delivery team knocking over a candelabra while setting up a wedding installation: that's a GL claim.
Most florists carry $1 million per occurrence and $2 million aggregate limits. Venue contracts for weddings and corporate events often require proof of these minimums, so carrying less can lock you out of your most profitable jobs.
Commercial Property for Inventory, Coolers, and Equipment
Your commercial property policy protects the physical assets inside your shop: floral inventory, walk-in coolers, refrigeration units, display cases, furniture, and signage. If a fire, burst pipe, or storm damages your space, this policy pays to repair or replace what's lost.
One detail florists often overlook is the value of their coolers. A commercial walk-in cooler can cost $15,000 to $30,000 to replace. Make sure your policy covers equipment at replacement cost, not depreciated value. Otherwise, you'll receive a check that barely covers half the price of a new unit.
Business Owner's Policy (BOP): The Cost-Effective Bundle
A BOP combines general liability and commercial property into a single policy, usually at a lower premium than buying them separately. For a small to mid-size flower shop, this is often the smartest entry point. BOPs typically include business interruption coverage, which replaces lost income if a covered event forces you to close temporarily.
The catch is that BOPs have eligibility limits. If your shop exceeds a certain revenue threshold or square footage, you may need standalone policies. Your agent can help you determine which structure saves the most without leaving gaps.
Mandatory New York State Requirements
New York doesn't leave employer coverage to your discretion. The state mandates several policies for any business with employees, and the penalties for non-compliance are steep.
Workers' Compensation for Shop Staff and Delivery Drivers
Every New York employer, even those with just one employee, must carry workers' compensation insurance. This policy covers medical expenses and lost wages when an employee is hurt on the job. For florists, common claims include repetitive strain injuries from cutting stems, back injuries from lifting heavy pots, and vehicle accidents during deliveries.
Here's some welcome news: New York businesses will see an average 22% reduction in workers' compensation premium rates starting October 1, 2026. That's a meaningful savings, especially for shops with several employees. Even with the rate drop, failing to carry this coverage can result in fines of $2,000 per 10-day period and even criminal charges. The New York Workers' Compensation Board maintains a universal authorization system to verify compliance, so there's no flying under the radar.
Disability and Paid Family Leave Benefits
New York also requires employers to provide short-term disability benefits (DBL) and Paid Family Leave (PFL). DBL covers a portion of wages when an employee can't work due to a non-work-related illness or injury. PFL provides paid time off for bonding with a new child, caring for a seriously ill family member, or addressing needs related to a family member's military deployment.
Both coverages can be obtained through the State Insurance Fund, a private carrier, or a self-insurance plan. Many florists bundle DBL and PFL with their workers' comp policy for simplicity. The cost is modest, often just a few dollars per employee per week, but the penalty for skipping it is a misdemeanor charge plus financial liability for any benefits owed.
Specialized Policies for Modern Flower Shops
The foundational and mandatory coverages handle the basics. These specialized policies address risks that are unique to how florists operate in 2026.
Commercial Auto for Delivery Vans and Hired Vehicles
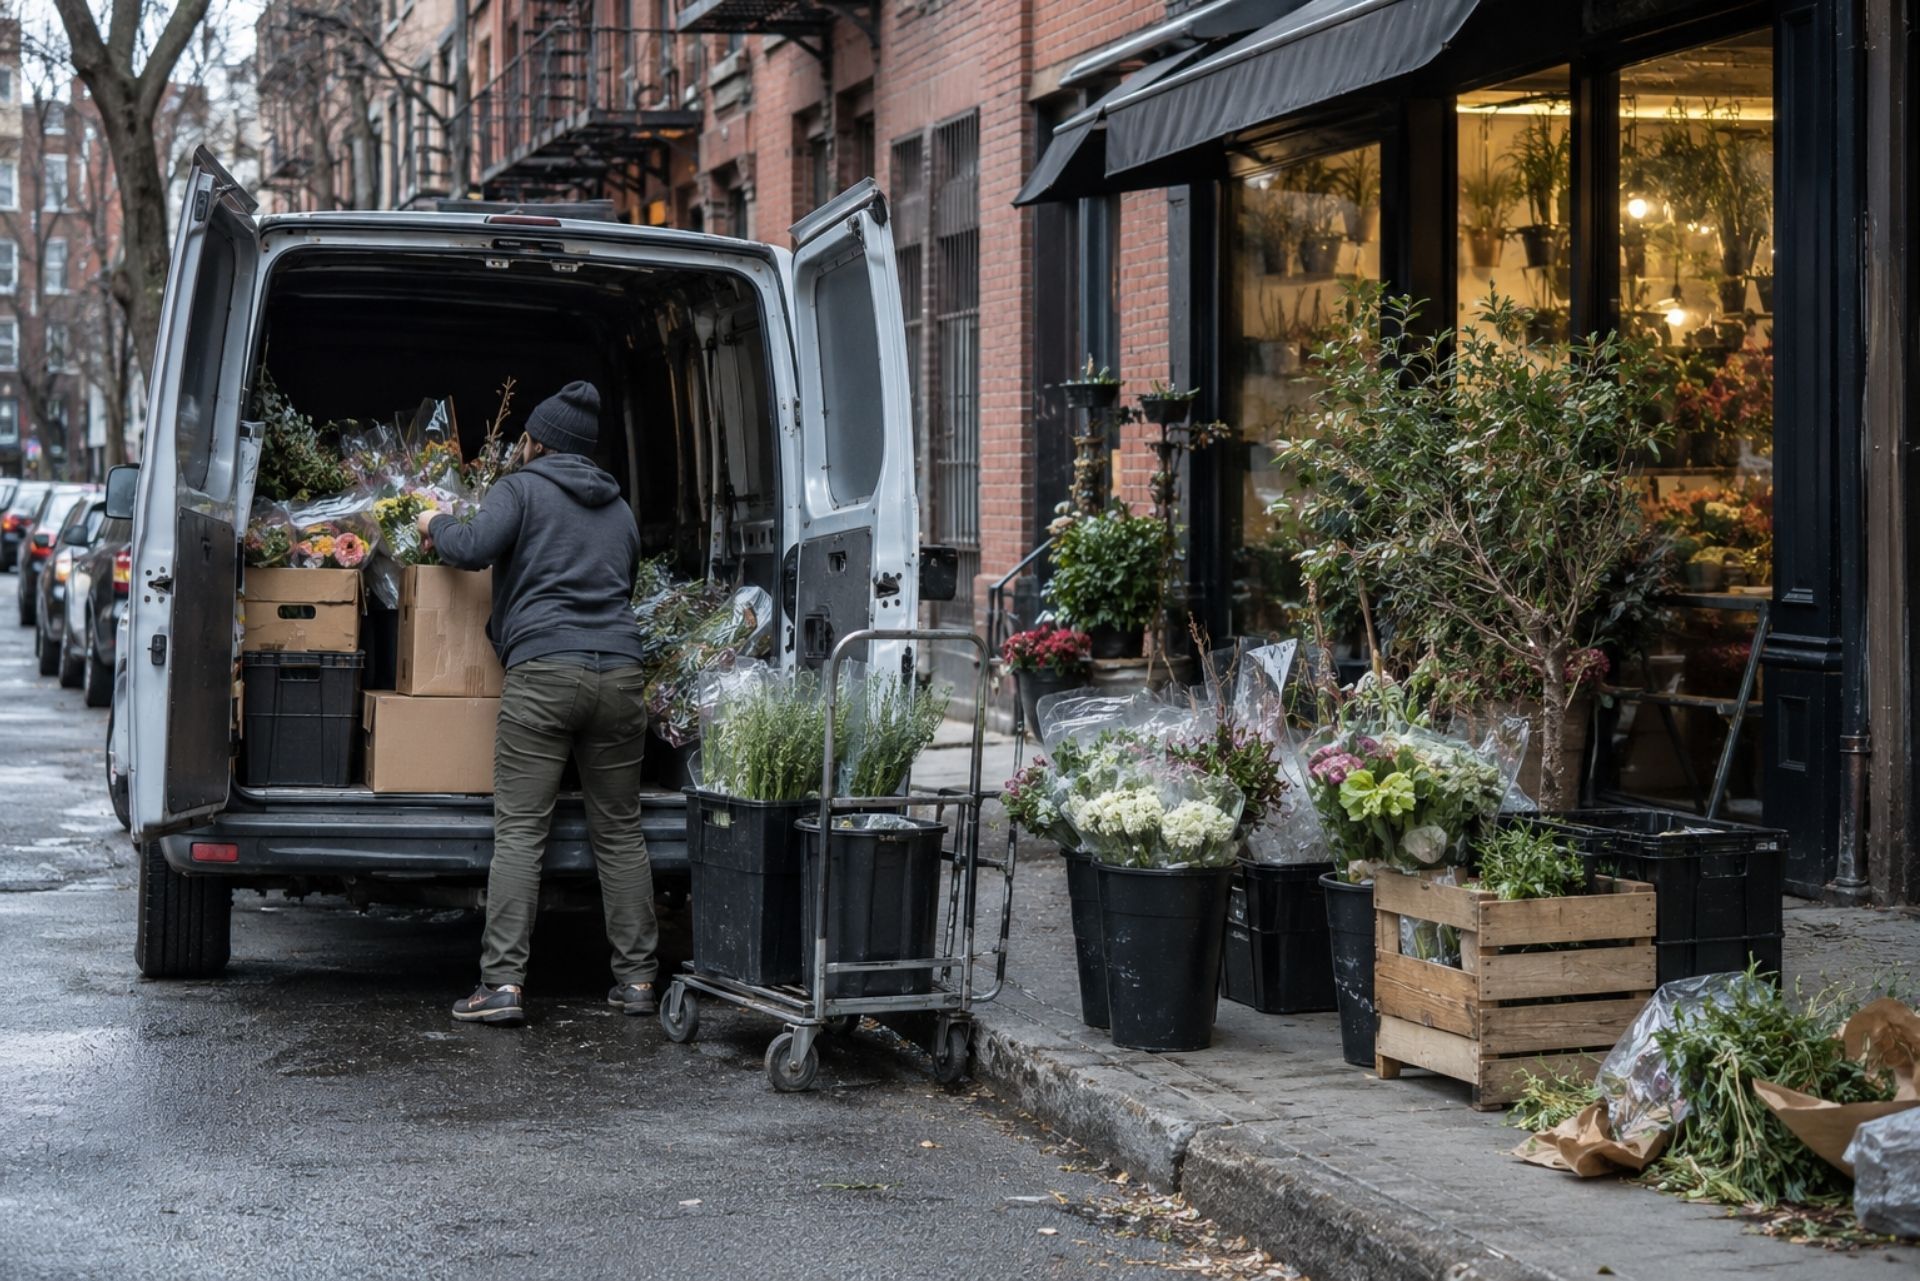
If your shop owns or leases delivery vehicles, you need a commercial auto policy. Personal auto insurance won't cover accidents that happen during business use, and your insurer can deny a claim if they discover the vehicle was making a delivery at the time of the crash.
New York's auto insurance rules are also changing. The NYDFS has issued guidance on 2026 motor vehicle insurance reforms that affect rate filings, fraud provisions, and serious injury thresholds. These sweeping reforms impact how accident claims are processed statewide, which could influence your premiums and coverage options. If you use employees' personal vehicles or hire third-party drivers during peak seasons like Valentine's Day and Mother's Day, consider hired and non-owned auto coverage as well.
Cyber Liability for E-commerce and POS Systems
A florist who takes online orders, stores customer payment data, or uses cloud-based inventory management is exposed to cyber risk. Cyber liability insurance covers the cost of breach notification, credit monitoring for affected customers, forensic investigation, legal defense, and regulatory fines.
NYC businesses are rethinking their cybersecurity insurance strategies in 2026 as ransomware attacks increasingly target small businesses. Many cyber policies now require you to meet baseline cybersecurity standards like multi-factor authentication and encrypted backups before they'll issue a policy. If you process even a modest volume of online orders, this coverage is no longer optional.
Spoilage Coverage for Temperature-Sensitive Stock
Standard property policies often exclude or severely limit coverage for spoilage. A dedicated spoilage endorsement or inland marine floater covers the value of perishable inventory lost due to equipment breakdown, power outages, or temperature fluctuations.
Consider a real scenario: a compressor failure in your walk-in cooler goes unnoticed over a holiday weekend. By Tuesday, you've lost $8,000 in premium roses, peonies, and imported orchids. Without spoilage coverage, that loss comes straight out of your pocket. This endorsement typically costs only a few hundred dollars per year, making it one of the best values in a florist's insurance program.
Comparison: Basic vs. Comprehensive Floral Coverage
| Coverage Type | Basic Package | Comprehensive Package |
|---|---|---|
| General Liability | $1M/$2M limits | $1M/$2M with umbrella to $5M |
| Commercial Property | Building and contents, named perils | Replacement cost, all-risk form |
| Workers' Compensation | State minimum | State minimum (required for all) |
| Commercial Auto | Liability only | Liability, collision, comprehensive, hired/non-owned |
| Cyber Liability | Not included | $500K-$1M limits |
| Spoilage | Not included | $10K-$25K sublimit |
| Business Interruption | Basic (included in BOP) | Extended with extra expense coverage |
| Disability/PFL | State minimum | State minimum (required for all) |
A basic package suits a single-location shop with minimal delivery and no online sales. Once you're running e-commerce, multiple vehicles, or high-value event work, the comprehensive approach protects you from the risks that actually threaten your business.
Common Questions About Florist Insurance in NY
How much does florist insurance cost in New York? A BOP for a small flower shop typically runs $1,200 to $3,000 per year. Adding commercial auto, cyber, and spoilage coverage can bring the total to $4,000 to $8,000, depending on your revenue, location, and number of employees.
Do I need insurance if I run a home-based floral business? Yes. Homeowner's insurance almost never covers business activities. You'll need at minimum a general liability policy and, if you have any employees, workers' comp and disability/PFL.
Can I use my personal car insurance for flower deliveries? No. Personal auto policies exclude business use. If you're in an accident while delivering an arrangement, your insurer can deny the claim entirely.
What happens if I don't carry workers' comp in New York? You face fines starting at $2,000 per 10-day period of non-compliance, potential criminal misdemeanor charges, and personal liability for any injured employee's medical bills and lost wages.
Is cyber insurance really necessary for a small florist? If you accept credit cards, process online orders, or store customer data electronically, yes. A single breach can cost $50,000 or more in notification, legal fees, and lost business, far more than an annual cyber premium.
Does my landlord's insurance cover my shop's contents? No. Your landlord's policy covers the building structure. Everything inside your leased space, from coolers to inventory to signage, is your responsibility to insure.
Making the Right Choice for Your Shop
The insurance a New York florist needs isn't a one-size-fits-all package. Your specific mix depends on whether you own or lease your space, how many employees you have, whether you operate delivery vehicles, and how much of your revenue comes through online channels. What doesn't change are the state mandates: workers' comp, disability, and paid family leave are non-negotiable for any shop with staff.
Start with a BOP to cover your general liability and property needs. Layer on commercial auto if you run deliveries, cyber liability if you sell online, and spoilage coverage to protect your most vulnerable asset: the flowers themselves. With the upcoming 22% workers' comp rate reduction this October, it's a good time to review your entire program and potentially redirect savings toward filling coverage gaps.
Get quotes from at least three agents or brokers who understand small retail and floral operations. Ask specifically about coverage exclusions, spoilage sublimits, and cyber policy prerequisites. The right insurance program won't just protect your shop from financial disaster: it'll give you the confidence to take on bigger events, hire more staff, and grow your business without losing sleep over what could go wrong.
ABOUT THE AUTHOR:
JELANI FENTON
As Owner of EG Bowman, I’m dedicated to continuing a legacy of trust and excellence built over more than seven decades. My focus is on helping businesses and individuals secure reliable, forward-thinking insurance solutions that protect their assets and support long-term growth.
Contact Us
OUR SERVICES
New York Business Insurance Coverage
General Liability Insurance


Workers Comp Insurance
Commercial Property Insurance
Commercial Auto Insurance
Commercial Umbrella Insurance
Business Owner's Policy
OUR SERVICES
New York Personal Insurance Coverage
Auto Insurance
Get coverage for your car and protect yourself on the road. We provide options for accidents, damages, and more.
Home Insurance
Protect your home and belongings with coverage for damages, theft, and unexpected events.
Umbrella Insurance
Extend your coverage with umbrella insurance for extra protection when you need it most.
Condo Insurance
Get peace of mind with condo insurance that protects your space and personal belongings.
NEW YORK BUSINESSES WE WORK WITH
Industries We Serve In New York
Electrician Insurance
Get coverage that protects electricians from accidents, property damage, and liability risks. Keep your tools, equipment, and business safe with plans designed for your needs. Request a quote to stay covered and focused on your work.
Real Estate Developer Insurance
Protect your projects with insurance that covers construction risks, liability, and property damage. We offer plans to keep your developments secure and on track. Get a quote to ensure your business is protected.
Wholesaler and Distributor Insurance
Protect your inventory and business operations with insurance that covers property damage and liability risks. Keep your supply chain running without disruptions. Get a quote to safeguard your business today.
What is an independent insurance agency, and how does it differ from a traditional insurance company?
An independent insurance agency works with multiple insurance carriers instead of just one. This allows us to provide customized coverage options tailored to your needs, rather than offering a one-size-fits-all policy. Independent agencies focus on finding the best value and coverage for their clients by comparing policies across various providers. At EG Bowman, we pride ourselves on offering personalized service and expertise to ensure our clients get the coverage that fits their specific needs.
What types of insurance does EG Bowman offer?
EG Bowman offers a wide range of insurance solutions, including commercial insurance, personal lines, property insurance, liability insurance, and specialized policies tailored to niche industries. Our focus is on protecting businesses and individuals from unforeseen risks. Whether you're looking for coverage for your home, car, or business, our team works to provide the most comprehensive and competitive options available. We’re here to make sure you’re prepared for the unexpected.
How does EG Bowman help businesses with insurance?
We specialize in understanding the unique risks businesses face and crafting insurance solutions to address them. From general liability to workers' compensation and industry-specific policies, our team ensures your business is protected at every level. We also provide risk management consultations to identify potential vulnerabilities and recommend solutions. With decades of experience, EG Bowman acts as a trusted partner, helping businesses navigate their insurance needs confidently.
Why should I choose EG Bowman as my insurance agency?
At EG Bowman, we combine decades of expertise with a client-focused approach to provide unparalleled service. Unlike larger, faceless companies, we build long-term relationships with our clients, offering personalized advice and solutions. We prioritize your needs, shop for the best rates, and advocate on your behalf when it comes to claims. Our goal is to be your trusted advisor in navigating insurance complexities and ensuring peace of mind.
How can I get a quote for insurance through EG Bowman?
Getting a quote with EG Bowman is simple and hassle-free. You can call us directly at 212-425-8150 or email us at info@egbowman.com to discuss your insurance needs. Our team will gather information about your situation and compare policies from multiple carriers to provide the best options. Whether it’s personal or business insurance, we ensure the process is transparent, efficient, and tailored to you.
Does EG Bowman offer insurance for small businesses?
Yes, EG Bowman specializes in working with small businesses. We understand the unique challenges small businesses face, from managing risks to staying within budget. Our insurance solutions cover everything from general liability to property insurance and more. By tailoring policies to fit your specific needs, we ensure your small business is well-protected while keeping costs manageable.
FAQS PAGE
Frequently Asked Questions
We understand you may have questions about our insurance services and how we can help protect what matters most to you. Below, you'll find answers to some of the most common questions we receive. If you don’t see the information you’re looking for, feel free to reach out to us directly. Our team is here to assist you with personalized advice and solutions.
NEWS & BLOG
Explore Our New York Insurance Blog
Contact Us