New York Uniform Rental Company Insurance
See How We're Different:
or Call Us: 212-425-8150
Most Common Business Policies
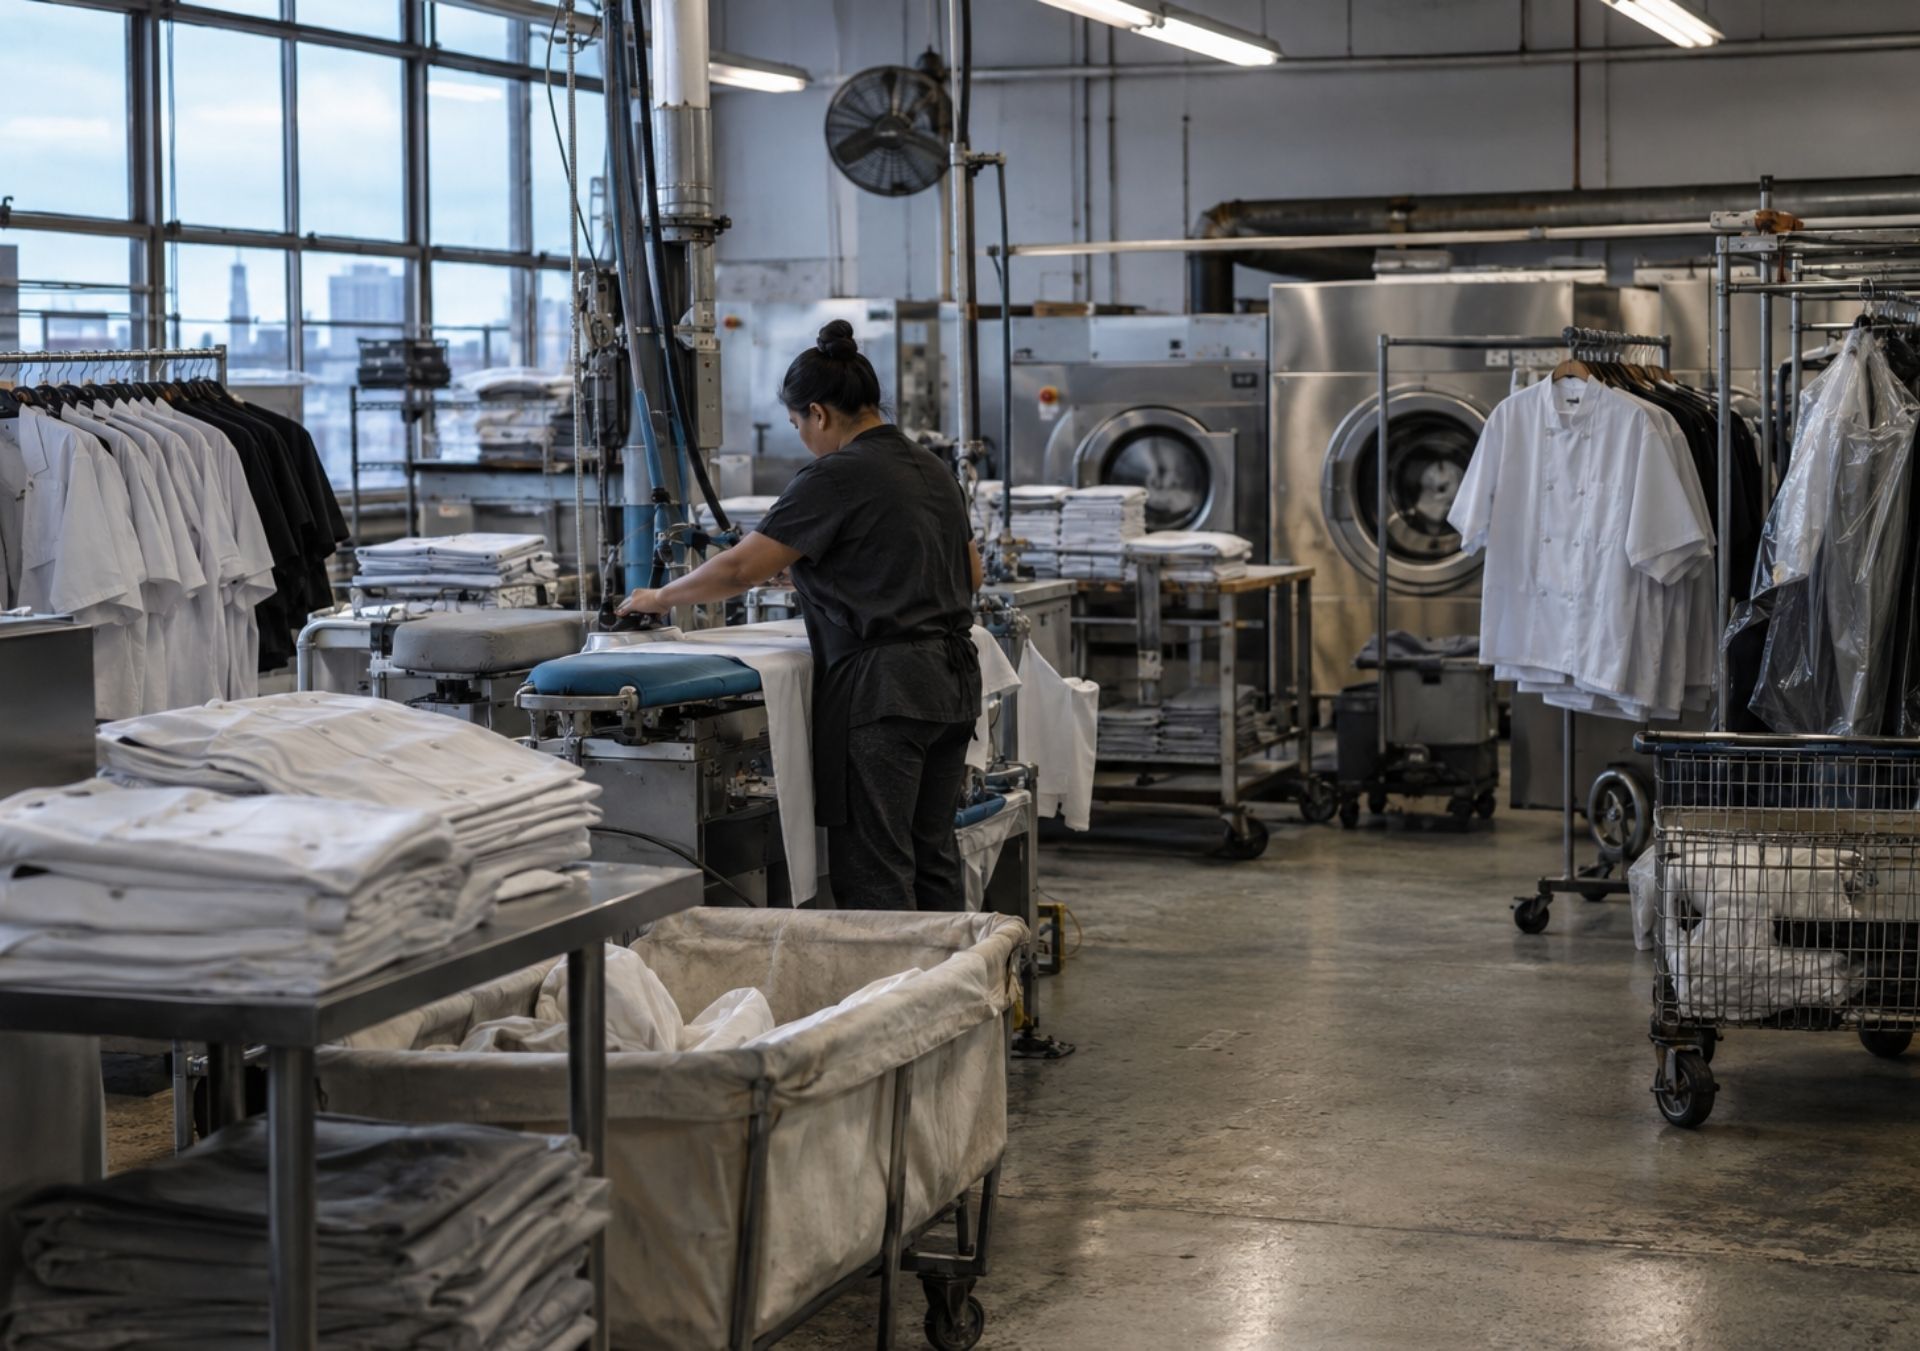
Running a uniform rental company in New York means managing risks that most business owners don't think about until it's too late. You're handling other people's property, running delivery trucks through congested city streets, processing payments with sensitive customer data, and operating industrial laundry equipment that can injure workers or damage neighboring properties. A single uninsured claim can cost more than a year's revenue.
If you're wondering what insurance a New York uniform rental company needs, the answer involves several interconnected policies: liability, property, auto, cyber, and workers' compensation coverage, at minimum. But the details matter more than the list. New York has some of the strictest regulatory requirements in the country, and general liability premiums for small service businesses in NYC average $890 per year, roughly 65% higher than the upstate median. That gap reflects the elevated litigation environment and population density that make the city a uniquely expensive place to operate without proper protection.
This guide breaks down each coverage type, highlights industry-specific policies most agents overlook, and gives you a clear framework for building a program that actually protects your business.
Core Insurance Requirements for New York Uniform Services
Every uniform rental operation faces a baseline set of exposures that standard commercial policies are designed to address. These aren't optional extras. They're the foundation your entire risk management strategy rests on, and New York regulators expect you to carry them.
The three pillars for any service business in the state are general liability, commercial property, and workers' compensation. Missing any one of them creates a gap that could shut you down, either through a lawsuit, a catastrophic loss, or a state enforcement action.
General Liability for Customer and Third-Party Risks
General liability insurance covers bodily injury and property damage claims from people outside your company. For a uniform rental business, this includes scenarios like a delivery driver tracking chemical residue into a client's lobby, a customer slipping on a wet floor at your storefront, or a batch of uniforms returned with chemical burns that damage a client's other garments.
New York courts are plaintiff-friendly, and slip-and-fall verdicts in the five boroughs regularly exceed six figures. Your general liability policy is your first line of defense against these claims, covering legal fees, settlements, and judgments up to your policy limit.
Most uniform rental companies should carry at least $1 million per occurrence and $2 million aggregate. If you serve hospitals, government agencies, or large commercial accounts, expect contract requirements pushing you toward $5 million or more, typically achieved by layering an umbrella policy on top of your primary coverage.
One mistake I see often: business owners assume their general liability policy covers damage to customer-owned uniforms in their care. It doesn't. That's a separate coverage called bailee's insurance, which we'll cover later.
Commercial Property Coverage for Laundry and Inventory
Your commercial property policy protects the physical assets that keep your operation running: the building (if you own it), industrial washers and dryers, pressing equipment, delivery vehicles stored on-site, and your uniform inventory. A fire in a laundry facility can easily cause $500,000 or more in equipment losses alone.
Commercial property premiums vary based on building construction, location, and total insured value. A concrete-block facility in Buffalo will cost far less to insure than a mixed-use building in Manhattan. Make sure your policy includes business income coverage, which replaces lost revenue while you rebuild or relocate after a covered loss.
Pay close attention to your policy's valuation method. Replacement cost coverage pays what it actually costs to buy new equipment. Actual cash value deducts depreciation, which means a five-year-old commercial dryer worth $15,000 new might only pay out $6,000. For a capital-intensive business like uniform rental, the difference can be devastating.
New York State Workers' Compensation Mandates
New York requires workers' compensation insurance for virtually every employer, with no minimum employee threshold. Even one part-time worker triggers the requirement. Operating without it is a criminal offense under New York Workers' Compensation Law Section 52, carrying fines of up to $2,000 per 10-day period of noncompliance.
Uniform rental employees face real occupational hazards: chemical burns from industrial detergents, repetitive motion injuries from sorting and pressing, back injuries from lifting heavy bags of soiled uniforms, and traffic accidents during deliveries. Workers' comp covers medical bills, lost wages, and rehabilitation costs for all of these.
Your premium is calculated using payroll and classification codes. Laundry workers and delivery drivers fall into different risk categories, so accurate employee classification matters. Misclassifying a driver as a
warehouse worker might save money short-term, but audits catch these errors, and the back-premiums plus penalties will cost far more than you saved.
Protecting Your Fleet and Digital Assets
Beyond the core policies, two exposures catch uniform rental companies off guard more than any others: vehicle accidents and data breaches. Both have grown more expensive to insure in recent years, and both carry consequences that extend well beyond the initial incident.
Commercial Auto Insurance for Delivery Routes
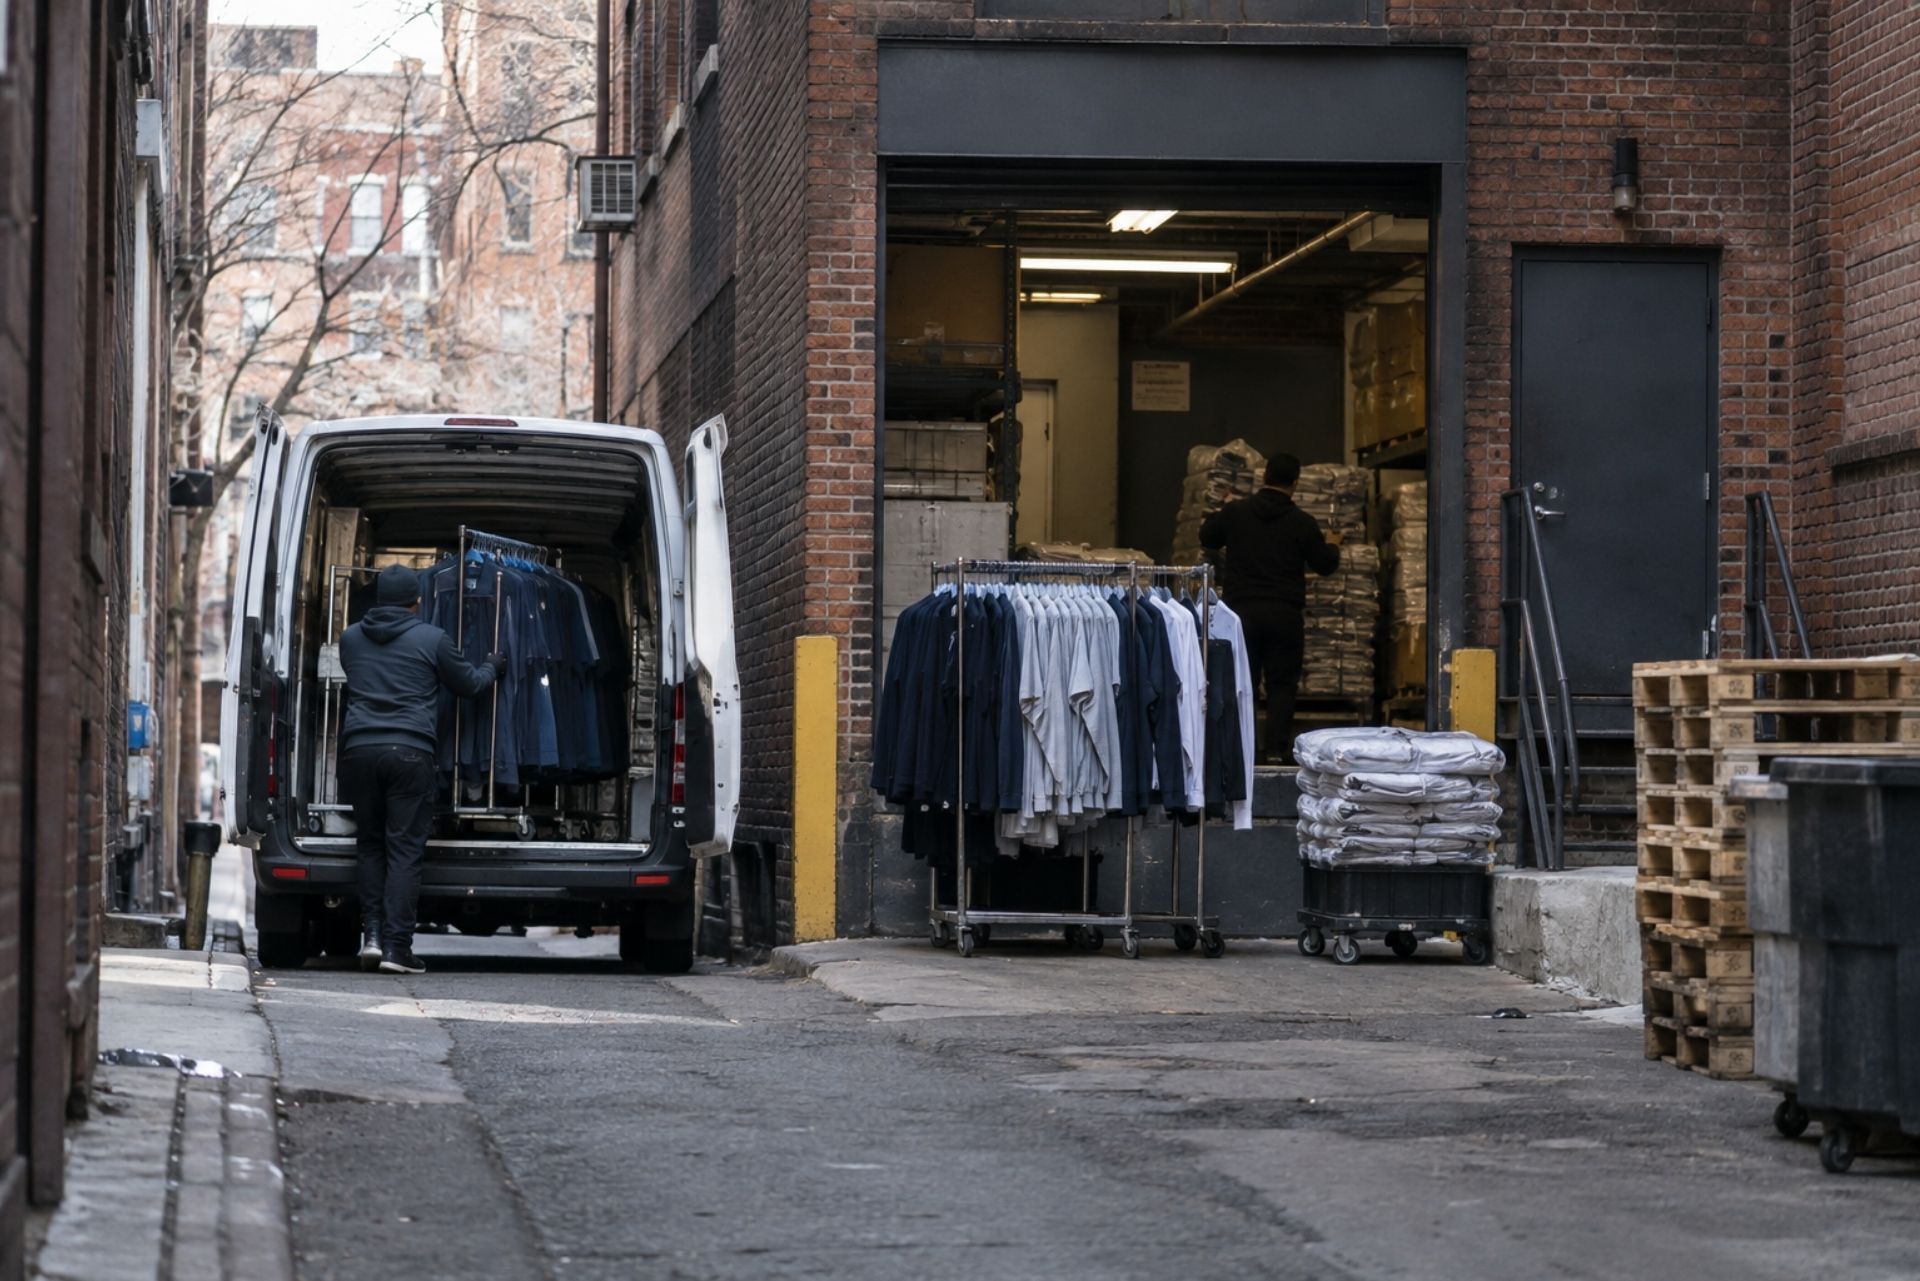
Your delivery fleet is the backbone of your business and one of your biggest liability exposures. Personal auto policies don't cover vehicles used for commercial purposes, so every truck, van, and car in your fleet needs a commercial auto policy.
New York's minimum liability limits for commercial vehicles are $25,000/$50,000 for bodily injury, but those minimums are dangerously low. A single accident involving a pedestrian in Manhattan can generate claims exceeding $1 million. Most insurers and risk advisors recommend carrying at least $1 million in combined single-limit coverage.
Hired and non-owned auto coverage is another piece many owners miss. If an employee uses their personal vehicle to run a work errand, pick up supplies, or make an emergency delivery, your business can be held liable for any accident they cause. This endorsement fills that gap at relatively low cost.
Route density matters for pricing, too. A fleet running daily routes through Midtown will pay significantly more than one covering suburban Long Island. If you can schedule deliveries during off-peak hours or consolidate routes, you may reduce both accident frequency and premiums.
Cyber Liability for Customer Payment Data
If you store customer credit card numbers, bank account details, or employee Social Security numbers, you're a target. Uniform rental companies often collect recurring payment information from hundreds of commercial accounts, making them attractive to cybercriminals even though they're not tech companies.
New York's SHIELD Act requires businesses that collect private information of New York residents to implement reasonable cybersecurity safeguards. A breach triggers mandatory notification requirements, and the costs add up fast: forensic investigation, customer notification, credit monitoring, legal defense, and potential regulatory fines.
A cyber liability policy covers these costs. It also typically includes access to breach response teams who can manage the crisis while you focus on keeping your business running. Insurance rate trends show
commercial premiums continuing to adjust as carriers recalibrate cyber risk, so locking in coverage sooner rather than later is smart planning.
Comparing Essential vs. Specialized Coverage
Comparison Table: Basic vs. Extended Protection
Not every policy carries the same weight for your business. Some are legally required, others are practically essential, and a few are industry-specific protections that most general agents won't mention unless you ask.
| Coverage Type | Basic Protection | Extended Protection |
|---|---|---|
| General Liability | $1M per occurrence / $2M aggregate | $5M+ with umbrella policy |
| Commercial Property | Actual cash value, basic perils | Replacement cost, business income, equipment breakdown |
| Workers' Comp | State-mandated minimums | Return-to-work programs, safety dividend plans |
| Commercial Auto | State minimum liability | $1M CSL, hired/non-owned, cargo coverage |
| Cyber Liability | $100K breach response | $1M+ with social engineering, funds transfer fraud |
| Bailee's Coverage | Not included | Covers customer-owned uniforms in your care |
| Pollution Liability | Not included | Covers chemical spills, wastewater discharge claims |
The basic column keeps you legal. The extended column keeps you solvent after a serious claim. Most established uniform rental companies need coverage closer to the extended side of this table.
Managing Risks Specific to the Uniform Rental Industry
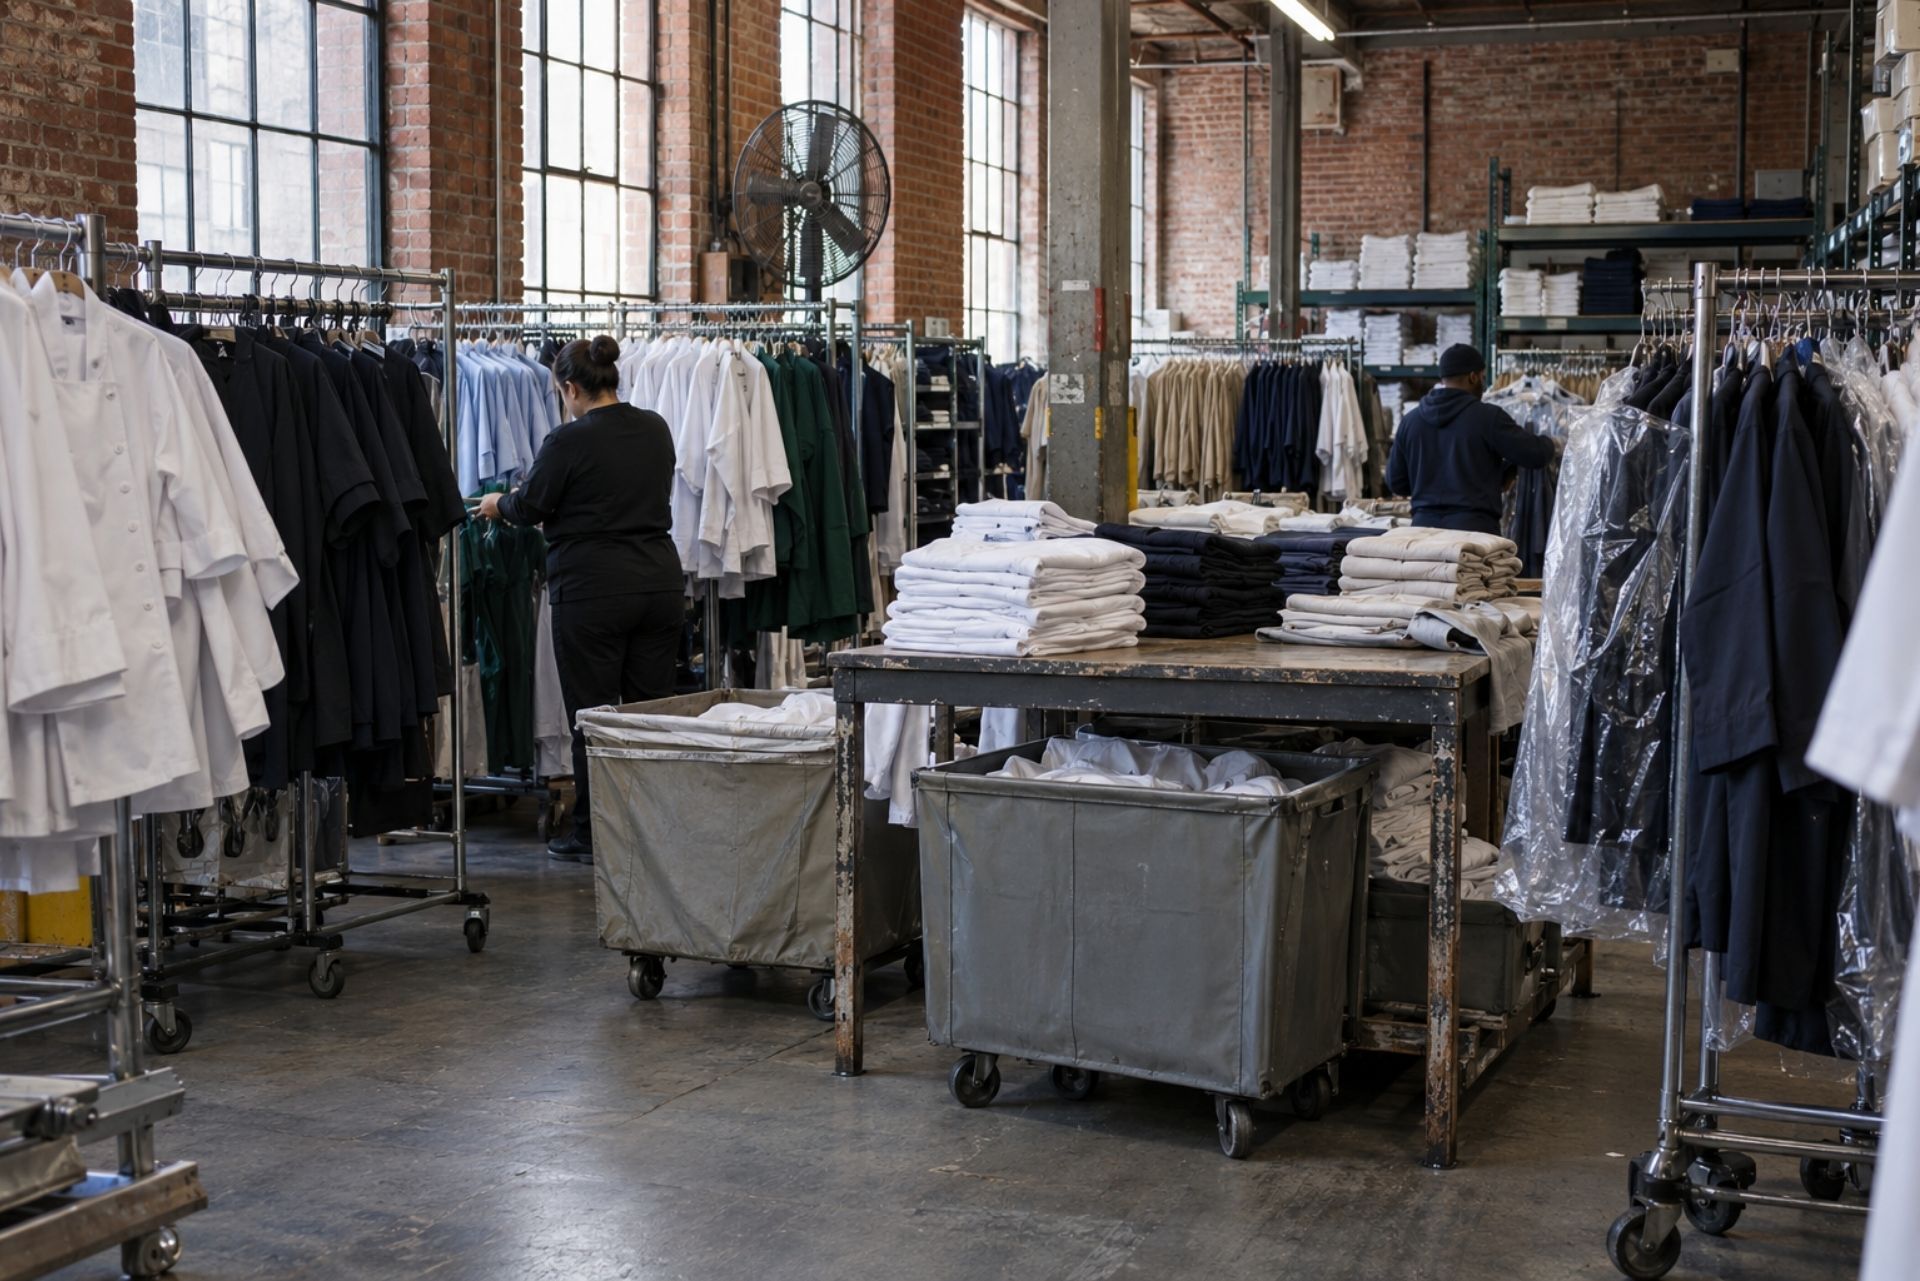
Generic business insurance programs miss two exposures that are central to what uniform rental companies actually do: holding other people's property and working with industrial chemicals daily.
Bailee's Coverage for Customer-Owned Goods
A bailee is someone who temporarily holds another person's property. Every time a customer hands you uniforms, linens, or specialty garments for cleaning, you become a bailee. Your general liability policy typically excludes damage to property in your care, custody, or control, which means a fire, flood, or equipment malfunction that destroys a client's inventory leaves you personally responsible for replacement costs.
Bailee's coverage fills this gap. It pays to replace or repair customer-owned goods damaged while in your possession. For a uniform rental company servicing dozens of commercial accounts, the total value of customer property on your premises at any given time can easily reach six figures.
Here's a real-world example: an industrial dryer malfunctions and scorches 200 flame-resistant coveralls belonging to an oil refinery client. Each coverall costs $85 to replace. That's $17,000 from a single equipment failure, and without bailee's coverage, it comes straight out of your pocket.
Pollution Liability for Industrial Cleaning Chemicals
Standard general liability policies contain pollution exclusions. If your facility uses industrial solvents, bleaching agents, or specialty cleaning chemicals, and those chemicals contaminate soil, groundwater, or a neighboring property, your GL policy won't respond.
Pollution liability insurance covers cleanup costs, third-party bodily injury, and property damage from chemical releases. New York's Department of Environmental Conservation can order remediation that costs hundreds of thousands of dollars, and the responsible party pays regardless of fault.
Wastewater discharge is another concern. Uniform rental facilities generate significant volumes of contaminated water. If your discharge violates local sewer authority limits, you could face fines, mandatory upgrades, and cleanup orders. A pollution policy with a wastewater endorsement addresses this exposure.
Common Questions About Uniform Rental Insurance
Does my landlord's insurance cover my equipment and inventory? No. Your landlord's policy protects the building structure, not your business property inside it. You need your own commercial property policy for equipment, inventory, and improvements you've made to the space.
Can I bundle all my policies with one carrier? Often, yes. A Business Owner's Policy (BOP) combines general liability and property coverage at a discount. Workers' comp, commercial auto, and specialty coverages like pollution liability are usually written separately but can often be placed through the same broker.
How much does workers' comp cost for uniform rental employees? Premiums depend on your payroll, classification codes, and claims history. Laundry workers and drivers carry different rates. A clean claims record and a formal safety program can reduce your experience modification factor, which directly lowers your premium.
Do I need cyber insurance if I don't sell online? Yes, if you store any customer payment data or employee personal information. A breach doesn't require an e-commerce site. Ransomware attacks target small businesses with weak network security, regardless of industry.
What happens if I operate without workers' comp in New York? The state can issue stop-work orders, impose fines up to $2,000 for every 10-day period you're uninsured, and hold you personally liable for any workplace injuries. It's treated as a criminal offense.
Is pollution liability really necessary for a laundry operation? If you use industrial chemicals, yes. A single spill or wastewater violation can trigger cleanup costs that dwarf the annual premium. Standard liability policies exclude pollution events entirely.
Making the Right Choice for Your Business
Building the right insurance program for a New York uniform rental company isn't about buying the cheapest policies available. It's about matching your actual exposures to the right coverages so a single bad day doesn't become a business-ending event.
Start with the non-negotiables: general liability, commercial property, workers' comp, and commercial auto. Then evaluate your specific operation for bailee's exposure, pollution risk, and cyber vulnerability. Most uniform rental businesses need all of these to some degree.
Work with a broker who understands the textile services industry, not just commercial insurance in general. An agent who's never written a bailee's policy or doesn't know what a pollution exclusion means will leave gaps in your coverage that you won't discover until you file a claim.
Review your program annually. Your payroll changes, your fleet grows, you add clients with new contract requirements, and insurance rates shift with market conditions. A policy that fit your business two years ago may not fit today. Schedule a yearly review with your broker, update your property valuations, and make sure your limits still match your exposure. The cost of being properly insured is always less than the cost of being caught without it.
ABOUT THE AUTHOR:
JELANI FENTON
As Owner of EG Bowman, I’m dedicated to continuing a legacy of trust and excellence built over more than seven decades. My focus is on helping businesses and individuals secure reliable, forward-thinking insurance solutions that protect their assets and support long-term growth.
Contact Us
OUR SERVICES
New York Business Insurance Coverage
General Liability Insurance


Workers Comp Insurance
Commercial Property Insurance
Commercial Auto Insurance
Commercial Umbrella Insurance
Business Owner's Policy
OUR SERVICES
New York Personal Insurance Coverage
Auto Insurance
Get coverage for your car and protect yourself on the road. We provide options for accidents, damages, and more.
Home Insurance
Protect your home and belongings with coverage for damages, theft, and unexpected events.
Umbrella Insurance
Extend your coverage with umbrella insurance for extra protection when you need it most.
Condo Insurance
Get peace of mind with condo insurance that protects your space and personal belongings.
NEW YORK BUSINESSES WE WORK WITH
Industries We Serve In New York
Electrician Insurance
Get coverage that protects electricians from accidents, property damage, and liability risks. Keep your tools, equipment, and business safe with plans designed for your needs. Request a quote to stay covered and focused on your work.
Real Estate Developer Insurance
Protect your projects with insurance that covers construction risks, liability, and property damage. We offer plans to keep your developments secure and on track. Get a quote to ensure your business is protected.
Wholesaler and Distributor Insurance
Protect your inventory and business operations with insurance that covers property damage and liability risks. Keep your supply chain running without disruptions. Get a quote to safeguard your business today.
What is an independent insurance agency, and how does it differ from a traditional insurance company?
An independent insurance agency works with multiple insurance carriers instead of just one. This allows us to provide customized coverage options tailored to your needs, rather than offering a one-size-fits-all policy. Independent agencies focus on finding the best value and coverage for their clients by comparing policies across various providers. At EG Bowman, we pride ourselves on offering personalized service and expertise to ensure our clients get the coverage that fits their specific needs.
What types of insurance does EG Bowman offer?
EG Bowman offers a wide range of insurance solutions, including commercial insurance, personal lines, property insurance, liability insurance, and specialized policies tailored to niche industries. Our focus is on protecting businesses and individuals from unforeseen risks. Whether you're looking for coverage for your home, car, or business, our team works to provide the most comprehensive and competitive options available. We’re here to make sure you’re prepared for the unexpected.
How does EG Bowman help businesses with insurance?
We specialize in understanding the unique risks businesses face and crafting insurance solutions to address them. From general liability to workers' compensation and industry-specific policies, our team ensures your business is protected at every level. We also provide risk management consultations to identify potential vulnerabilities and recommend solutions. With decades of experience, EG Bowman acts as a trusted partner, helping businesses navigate their insurance needs confidently.
Why should I choose EG Bowman as my insurance agency?
At EG Bowman, we combine decades of expertise with a client-focused approach to provide unparalleled service. Unlike larger, faceless companies, we build long-term relationships with our clients, offering personalized advice and solutions. We prioritize your needs, shop for the best rates, and advocate on your behalf when it comes to claims. Our goal is to be your trusted advisor in navigating insurance complexities and ensuring peace of mind.
How can I get a quote for insurance through EG Bowman?
Getting a quote with EG Bowman is simple and hassle-free. You can call us directly at 212-425-8150 or email us at info@egbowman.com to discuss your insurance needs. Our team will gather information about your situation and compare policies from multiple carriers to provide the best options. Whether it’s personal or business insurance, we ensure the process is transparent, efficient, and tailored to you.
Does EG Bowman offer insurance for small businesses?
Yes, EG Bowman specializes in working with small businesses. We understand the unique challenges small businesses face, from managing risks to staying within budget. Our insurance solutions cover everything from general liability to property insurance and more. By tailoring policies to fit your specific needs, we ensure your small business is well-protected while keeping costs manageable.
FAQS PAGE
Frequently Asked Questions
We understand you may have questions about our insurance services and how we can help protect what matters most to you. Below, you'll find answers to some of the most common questions we receive. If you don’t see the information you’re looking for, feel free to reach out to us directly. Our team is here to assist you with personalized advice and solutions.
NEWS & BLOG
Explore Our New York Insurance Blog
Contact Us