New York Recycling Center Insurance
See How We're Different:
or Call Us: 212-425-8150
Most Common Business Policies
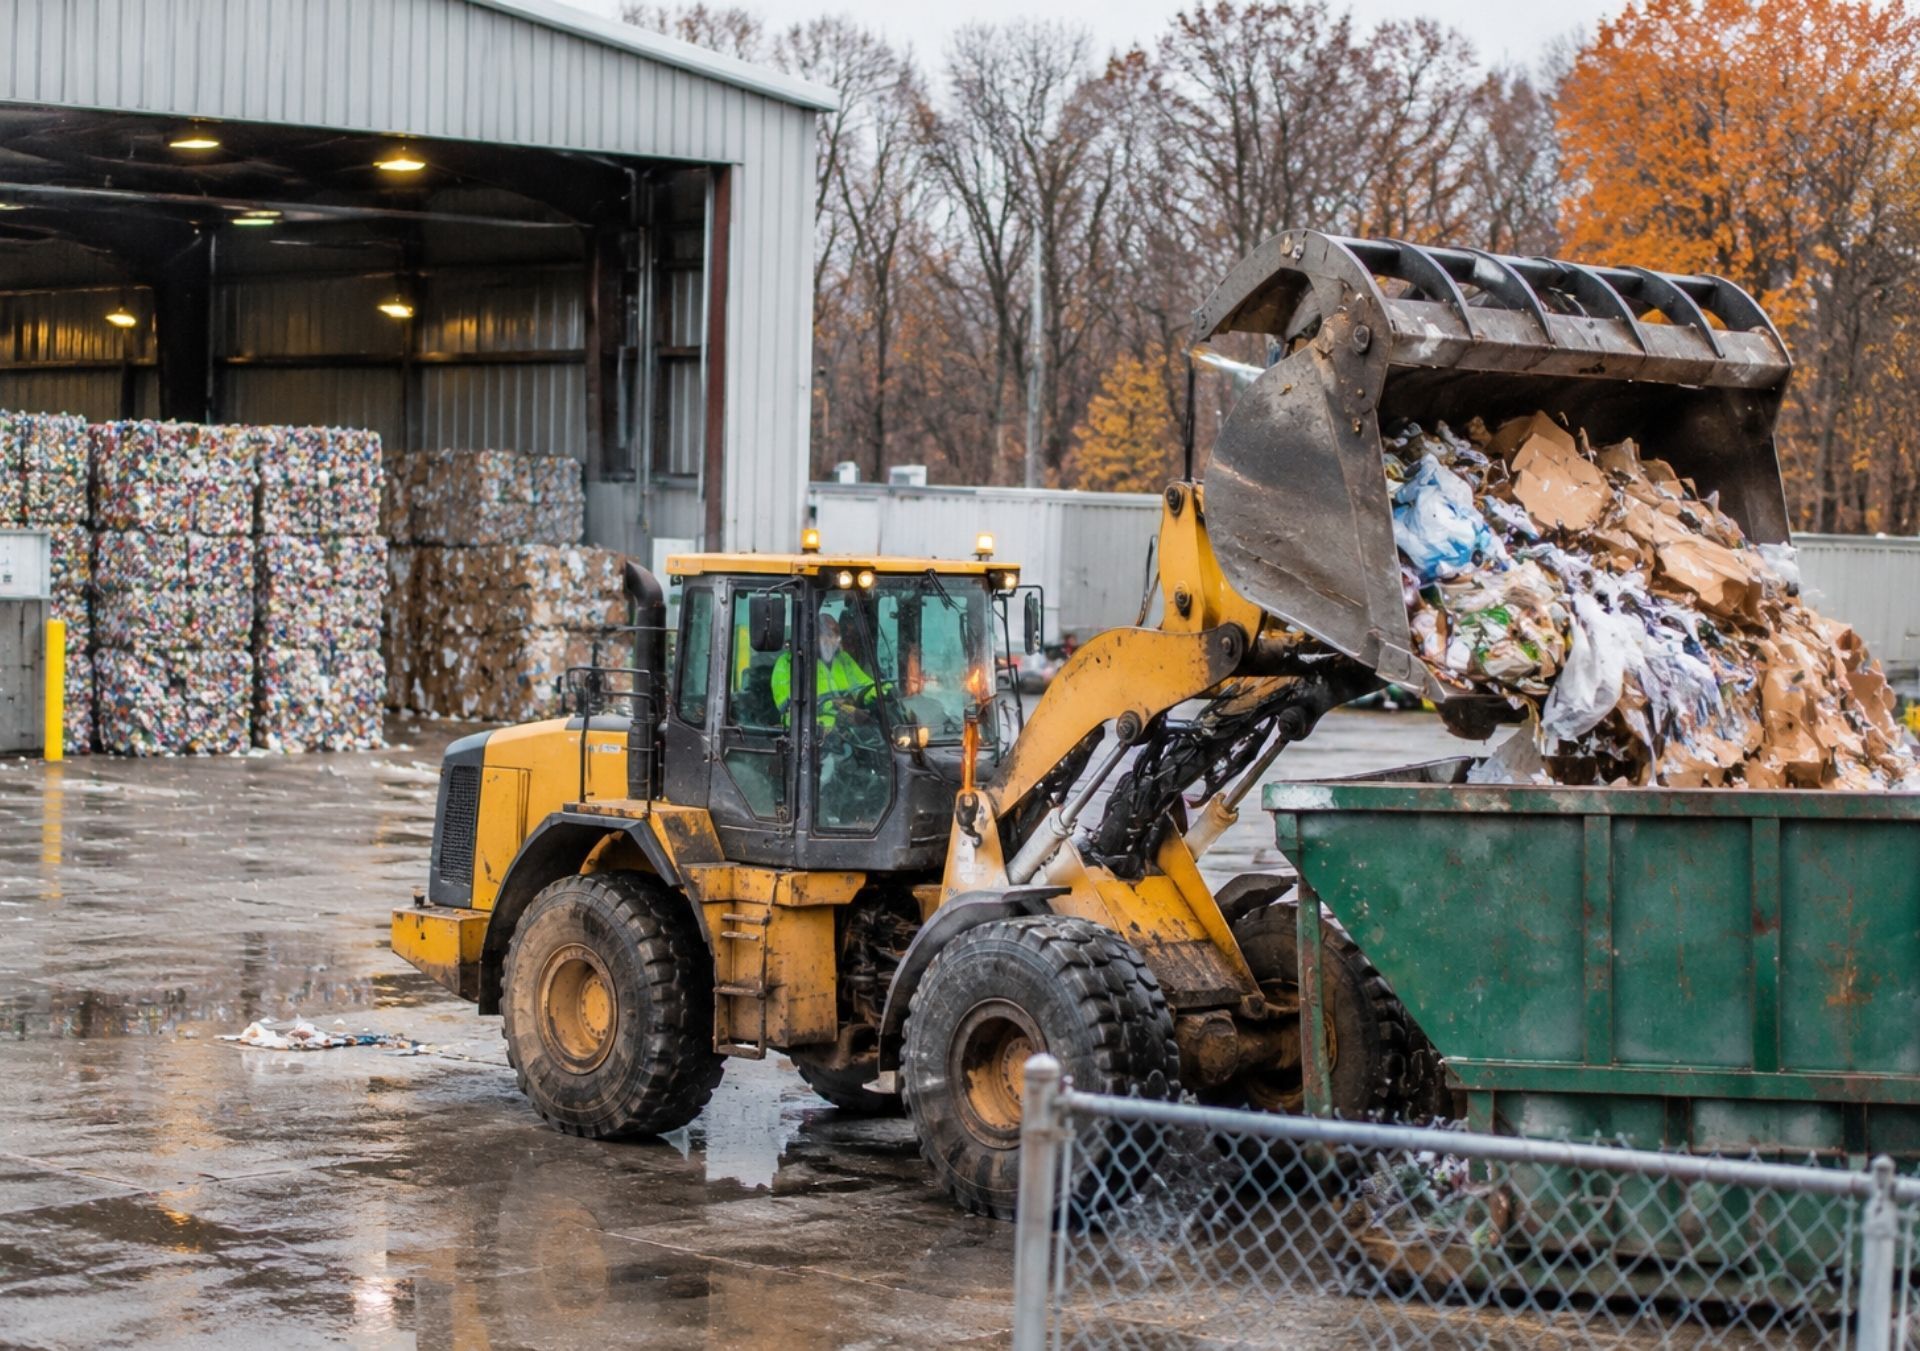
Picture a bale of mixed plastics smoldering overnight on your tipping floor because one disposable vape slipped past the sort line. By morning, you're facing a burned conveyor, a shutdown, a neighbor's
damaged warehouse, and an injured employee. If you've ever wondered what insurance a New York recycling center needs, that single scenario touches nearly every policy you'll carry. Here's how liability, property, auto, cyber, and workers' compensation fit together for your operation in 2026.
Core Liability and Property Risks for NY Recycling Facilities
Recycling facilities sit in a tough underwriting class. You handle unpredictable material streams, run heavy equipment, host public drop-off traffic, and operate under some of the strictest state regulations in the country. Carriers know this, so the details of your coverage matter more than the premium.
Protecting Physical Assets and Heavy Machinery
Fire is the claim that keeps underwriters up at night. The FDNY reported a 70% increase in lithium-ion battery fire investigations through July 2026 compared to the same period in 2025. Your commercial property policy should cover the building, balers, shredders, optical sorters, and stored inventory at replacement cost, not actual cash value.
Watch for these common gaps:
- Business income coverage that's too short to cover a six-month equipment rebuild
- Equipment breakdown excluded from the base policy
- Inland marine coverage missing for mobile loaders and roll-off containers
- Fire suppression warranties that void coverage if sprinklers aren't maintained
General Liability vs. Environmental Pollution Coverage
General liability covers third-party bodily injury and property damage, like a resident slipping at your drop-off area. It doesn't cover pollution. Most standard GL policies now carry ISO Form CG 40 32 05 23, which excludes PFAS-related injury and damage.
That exclusion bites hard. Recycling centers are seen as passive receivers of PFAS, yet they remain highly vulnerable to private lawsuits despite some federal carve-outs. A standalone pollution liability policy fills that gap. Ask specifically how it treats PFAS, since many carriers are narrowing that coverage too.
You'll also need financial assurance. Under NYS DEC Part 360, facilities must maintain
annual financial assurance instruments, such as surety bonds or letters of credit, to cover third-party closure costs. That's a bond, not insurance, but your broker should handle both.
New York State Mandates: Workers' Comp and Commercial Auto
New York requires workers' compensation for nearly every employer, and penalties for lapses run steep. The good news: Governor Hochul announced a 22% average decrease in workers' comp loss cost rates effective October 1, 2026, expected to save businesses over $1 billion annually. Your actual premium still depends on your experience modification and class codes.
The catch is that recycling work generates serious injuries: crushed hands in balers, forklift strikes, and lacerations from sorting. Misclassifying sorters as clerical staff is a mistake that shows up during audits and leads to large back-premium bills. Don't forget disability and Paid Family Leave, which New York also mandates.
Commercial auto is required for every truck you own. If employees drive personal vehicles to pick up materials, add
hired and non-owned auto. Collection trucks backing into parked cars or utility poles are a frequent claim type, and NYC routes typically carry higher premiums than upstate routes because of congestion and litigation costs.
Modern Threats: Cyber Liability and Data Protectio
Most recycling owners assume they're not a hacking target. Then ransomware locks the scale software and you can't weigh loads, issue tickets, or pay customers for scrap. That's lost revenue every hour the system stays down.
Your data exposure is bigger than you think. Scrap operations often store driver's license scans, vehicle details, and payment information for sellers. A breach triggers New York's notification requirements and possible regulatory scrutiny.
The state is raising expectations. In May 2026, NY DFS issued guidance requiring regulated entities to account for Frontier AI models in their cybersecurity risk assessments. Even if DFS doesn't regulate you directly, carriers are borrowing those standards for their applications. Expect questions about multi-factor authentication, offline backups, and employee phishing training.
A solid cyber policy should include:
- Ransomware response and negotiation
- Business interruption from system downtime
- Data breach notification costs
- Funds transfer fraud coverage
Comparison of Standard vs. Enhanced Recycling Insurance
Here's how a basic package stacks up against one built for real recycling risks.
| Coverage Area | Standard Package | Enhanced Package |
|---|---|---|
| Property | Actual cash value | Replacement cost plus equipment breakdown |
| Business Income | 3 to 6 months | 12 months or more |
| General Liability | PFAS excluded | Paired with pollution policy |
| Pollution | Not included | Standalone, PFAS terms reviewed |
| Auto | Owned vehicles only | Owned, hired, and non-owned |
| Cyber | Often none | Ransomware and downtime included |
| Umbrella | Low limits | Higher limits sized to NY verdicts |
The standard column might satisfy a lease. The enhanced column is what keeps your doors open after a major fire or lawsuit.
Common Questions About Recycling Center Insuranc
Does general liability cover a fire that spreads to my neighbor's property? Usually yes, for property damage caused by the fire itself. If contamination is involved, you'll need pollution coverage.
Why is my property premium rising even without claims? Battery-driven fires are rising across the industry. The vape effect is a primary driver of a 26% increase in reported fire incidents between 2022 and 2026.
Do I need workers' comp if I only have part-time sorters? Yes. New York requires coverage for part-time employees too.
Is a surety bond the same as insurance? No. A bond protects the state and third parties, and you repay the surety for any claim it pays.
Will my insurer care about my battery screening process? Absolutely expect questions on it. Documented screening, thermal cameras, and suppression systems can improve your terms.
Making the Right Choice for Your Facility
New Your coverage should match how your facility actually operates, not a generic template. Start with a fire and pollution review, since those two exposures cause the largest losses. Then confirm your workers' comp class codes are accurate before the October rate change takes effect.
Next steps to take this quarter:
- Request a written PFAS exclusion review from your broker
- Verify your Part 360 financial assurance is current
- Test your cyber backups and document MFA use
- Update equipment values for replacement cost
A specialist broker who knows New York recycling coverage can spot gaps a general agent misses. Book that review now, before your next renewal or your next fire forces the conversation.
ABOUT THE AUTHOR:
JELANI FENTON
As Owner of EG Bowman, I’m dedicated to continuing a legacy of trust and excellence built over more than seven decades. My focus is on helping businesses and individuals secure reliable, forward-thinking insurance solutions that protect their assets and support long-term growth.
Contact Us
OUR SERVICES
New York Business Insurance Coverage
General Liability Insurance


Workers Comp Insurance
Commercial Property Insurance
Commercial Auto Insurance
Commercial Umbrella Insurance
Business Owner's Policy
OUR SERVICES
New York Personal Insurance Coverage
Auto Insurance
Get coverage for your car and protect yourself on the road. We provide options for accidents, damages, and more.
Home Insurance
Protect your home and belongings with coverage for damages, theft, and unexpected events.
Umbrella Insurance
Extend your coverage with umbrella insurance for extra protection when you need it most.
Condo Insurance
Get peace of mind with condo insurance that protects your space and personal belongings.
NEW YORK BUSINESSES WE WORK WITH
Industries We Serve In New York
Electrician Insurance
Get coverage that protects electricians from accidents, property damage, and liability risks. Keep your tools, equipment, and business safe with plans designed for your needs. Request a quote to stay covered and focused on your work.
Real Estate Developer Insurance
Protect your projects with insurance that covers construction risks, liability, and property damage. We offer plans to keep your developments secure and on track. Get a quote to ensure your business is protected.
Wholesaler and Distributor Insurance
Protect your inventory and business operations with insurance that covers property damage and liability risks. Keep your supply chain running without disruptions. Get a quote to safeguard your business today.
What is an independent insurance agency, and how does it differ from a traditional insurance company?
An independent insurance agency works with multiple insurance carriers instead of just one. This allows us to provide customized coverage options tailored to your needs, rather than offering a one-size-fits-all policy. Independent agencies focus on finding the best value and coverage for their clients by comparing policies across various providers. At EG Bowman, we pride ourselves on offering personalized service and expertise to ensure our clients get the coverage that fits their specific needs.
What types of insurance does EG Bowman offer?
EG Bowman offers a wide range of insurance solutions, including commercial insurance, personal lines, property insurance, liability insurance, and specialized policies tailored to niche industries. Our focus is on protecting businesses and individuals from unforeseen risks. Whether you're looking for coverage for your home, car, or business, our team works to provide the most comprehensive and competitive options available. We’re here to make sure you’re prepared for the unexpected.
How does EG Bowman help businesses with insurance?
We specialize in understanding the unique risks businesses face and crafting insurance solutions to address them. From general liability to workers' compensation and industry-specific policies, our team ensures your business is protected at every level. We also provide risk management consultations to identify potential vulnerabilities and recommend solutions. With decades of experience, EG Bowman acts as a trusted partner, helping businesses navigate their insurance needs confidently.
Why should I choose EG Bowman as my insurance agency?
At EG Bowman, we combine decades of expertise with a client-focused approach to provide unparalleled service. Unlike larger, faceless companies, we build long-term relationships with our clients, offering personalized advice and solutions. We prioritize your needs, shop for the best rates, and advocate on your behalf when it comes to claims. Our goal is to be your trusted advisor in navigating insurance complexities and ensuring peace of mind.
How can I get a quote for insurance through EG Bowman?
Getting a quote with EG Bowman is simple and hassle-free. You can call us directly at 212-425-8150 or email us at info@egbowman.com to discuss your insurance needs. Our team will gather information about your situation and compare policies from multiple carriers to provide the best options. Whether it’s personal or business insurance, we ensure the process is transparent, efficient, and tailored to you.
Does EG Bowman offer insurance for small businesses?
Yes, EG Bowman specializes in working with small businesses. We understand the unique challenges small businesses face, from managing risks to staying within budget. Our insurance solutions cover everything from general liability to property insurance and more. By tailoring policies to fit your specific needs, we ensure your small business is well-protected while keeping costs manageable.
FAQS PAGE
Frequently Asked Questions
We understand you may have questions about our insurance services and how we can help protect what matters most to you. Below, you'll find answers to some of the most common questions we receive. If you don’t see the information you’re looking for, feel free to reach out to us directly. Our team is here to assist you with personalized advice and solutions.
NEWS & BLOG
Explore Our New York Insurance Blog
Contact Us